When to Apply for Your Next Credit Card (Avoid This Mistake)
A lot of people treat credit card applications like it’s no big deal. See a shiny welcome bonus, click apply, hope for instant approval. Then three weeks later, they’re applying again somewhere else because another offer popped up on YouTube or Social Media.
That’s usually where things start going sideways.
The timing between credit card applications matters way more than most people realise. Not just for approvals either. It affects your credit score, how banks see you, and even the kind of limits you’ll get offered later.
The simple version?
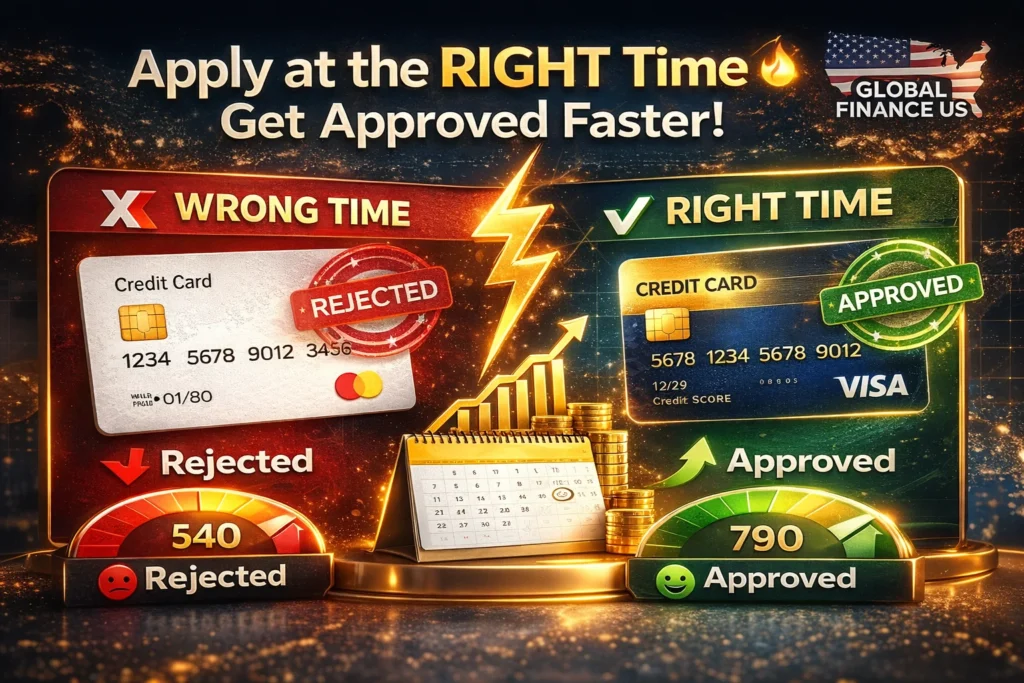
For most people, waiting around 6 months between applications is the safest move.
Not because banks have some magical timer. It’s because your credit profile needs breathing room.
Easy & Fast Guide to the Best Credit Card Application Timing
Why the 6-Month Rule Actually Helps
Every time you apply for a credit card, the lender does a hard inquiry on your credit report.
That inquiry can shave a few points off your FICO score. Usually not enough to panic over, but if you stack multiple applications close together, those small hits add up fast.
And honestly, lenders notice the pattern more than the score drop itself.
If your report suddenly shows three or four recent applications, it can make you look financially stressed. Even if you’re not.
From a bank’s perspective, someone aggressively applying for credit might be:
- carrying too much debt
- struggling with cash flow
- preparing to borrow heavily
- chasing credit because they were denied elsewhere
Banks don’t love uncertainty. So approvals get harder.
Waiting about 6 months gives your score time to recover and makes your profile look more stable. It also helps build trust with lenders over time, which matters more than people think.
If you recently closed a card and plan to apply again later, make sure you understand issuer waiting periods and reapplication rules first. Read our ultimate guide to reapplying for a credit card .
But What If You Have Excellent Credit?
This is where things get a little more flexible.
If you’ve got:
- a high credit score
- strong income
- low debt
- perfect payment history
…you can sometimes apply more often without major issues.
Some people in the credit card rewards world apply every 3 months and still rack up approvals. But they usually have very clean credit profiles and years of history backing them up.
That part gets left out online a lot.
People see someone bragging about opening five cards in a year and assume everyone can do it. Not true.
Even with excellent credit, too many applications too quickly can still trigger denials or lower limits. Some banks also have their own internal rules. Chase, for example, is known for being stricter if you’ve opened too many recent accounts.
So yeah, having good credit gives you more room to move. It doesn’t make you invisible.
Your existing credit profile also affects how much damage frequent applications or cancellations can cause. Users with stronger credit histories usually have more flexibility. Read our guide on canceling a credit card after approval .
When You’re Rebuilding Credit
If your score already needs work, rapid applications usually make things worse.
A better strategy:
- pay every bill on time
- lower your balances
- keep utilization low
- let your accounts age naturally
Slow improvement beats panic-applying for random cards.
When Your Score Is Already Low
Hard inquiries hit harder when your score is struggling.
Someone with a 790 score can absorb a small drop pretty easily. Someone sitting around 580 or 620 doesn’t have the same cushion.
In that situation, waiting longer — sometimes even 12 months — can genuinely help.
Not exciting advice, but usually the smart move.
What To Do If You Get Rejected
The worst thing you can do after a denial is immediately apply somewhere else out of frustration.
A lot of people spiral into this:
“Okay, Capital One said no… maybe Discover will approve me… okay maybe Amex…”
That chain reaction can damage your score pretty quickly.
Instead, pause and figure out why you were denied.
Usually the lender will send a notice explaining the main reasons, like:
- high utilization
- too many inquiries
- short credit history
- missed payments
- insufficient income
Fix the actual issue first.
Then give your credit profile time to recover before applying again. Around 6 months is generally a safer window.
Patience sounds boring in personal finance, but it saves people from making expensive mistakes.
Disclaimer: The information provided in this article by Global Finance US (GFU) is for general educational and informational purposes only and should not be considered financial, legal, or credit advice. Credit card approvals, application timing, credit score impacts, lender policies, and approval requirements may vary depending on the credit card issuer and your financial profile. Always review the official terms and conditions before applying for any credit card. Global Finance US does not guarantee approvals or financial outcomes based on the information shared in this article.
Free Mortgage Calculator (USA) – Estimate Your Home Loan Fast
Use ourmortgage calculatorto estimate yourmonthly payment, interest cost, and total loan amount. Plan your home purchase with accurate home loan, interest rate, and EMI calculations in seconds.Perfect for buyers in the USA looking to compare mortgage rates and save money.
Read More →Terms apply. Based on your credit score.